Identity theft

The first few hours decide most of it. What you do before reporting matters more than the procedure that follows.

Illustration: Identity theft

Appear on this page

Get our daily news watch

An offence that does not exist everywhere

Many countries have no standalone offence of identity theft: what is prosecuted is the fraud committed afterwards — deception, forgery, unauthorised access to a computer. Others have created a specific offence that bites before any financial loss appears, as soon as the identity information is obtained or used. The difference changes how you write the report: in the first case you must describe the fraudulent act, in the second the use of your identity is enough.

The order of steps, which matters more than the law

Three priorities, in this order. First the email account: it resets everything else, and until it is secured nothing else is safe. Then the payment instruments: block them immediately and confirm in writing, because in almost every system reimbursement depends on how fast you reported. Finally the credit and identity files: asking what is recorded in your name is the only way to discover accounts opened by someone else.

The phone is the main way in
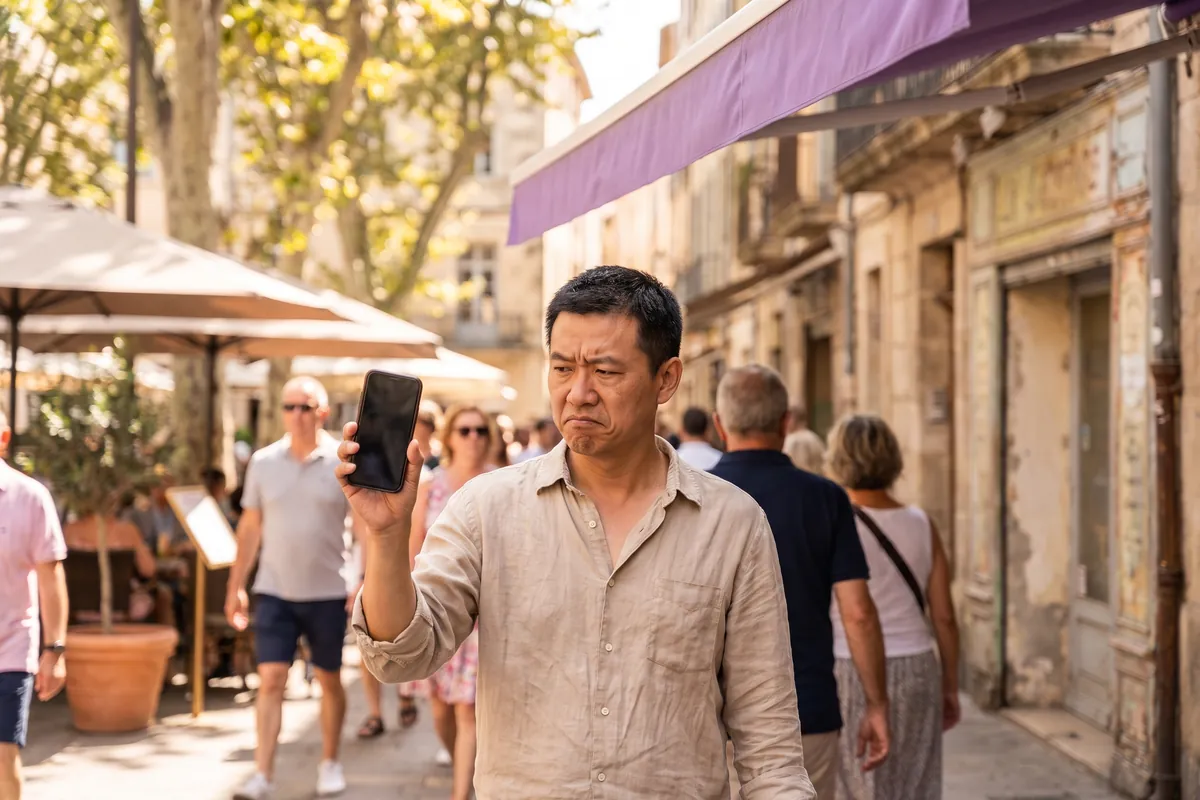
A man stops in the middle of a busy street and raises his phone, puzzled, as if looking for a signal
An unexplained loss of signal should alert you: call your operator from another phone.

A growing share of fraud runs through the phone number: a hijacked line, a duplicated SIM, intercepted one-time codes. The warning sign is simple and widely ignored: an unexplained loss of network while the handset still works. If that happens, call the operator from another phone immediately. Where money moves by mobile, the window to stop a transfer is measured in minutes.

Repair takes longer than the fraud

The long part is not the fraud, it is putting things right: removing incorrect entries, cancelling contracts, proving that an application was not yours. Two rules help. Everything in writing, with proof of posting, never by phone alone. And a single chronological file holding every letter, reference and acknowledgement: it is that file, not the police report, that everyone will ask you for.

The single most protective step

Where it is available, place a freeze or block on new credit in your name with the credit bureaus or a fraud prevention service. It stops more fraudulent applications than anything else and is usually free. Note the expiry date: these blocks are often temporary and lapse without warning.

The law country by country

The legal framework, the procedure, the time limits and the costs differ from one country to another. Each country below has a detailed page: governing texts, key facts, the actual procedure, costs, where to go and the traps to avoid.

Select a country to open its detailed page.
European framework

European Union

The Union has not harmonised identity theft as such, but it requires the punishment of illegal access to an account, which is almost always the starting point.

Europe

Ireland

Prosecuted as deception and fraud offences; the Central Credit Register lets you see loans taken out in your name.

United Kingdom

Identity theft is not itself a crime — the fraud committed with your identity is. Protective registration is the practical defence.

Western Africa

Ghana

The Cybersecurity Act and the criminal code cover impersonation; the Ghana Card and mobile money are the pressure points.

Nigeria

The Cybercrimes Act punishes identity theft and impersonation, with BVN and NIN misuse the central practical risk.

Eastern Africa

Kenya

Specific offences for identity theft and impersonation, with mobile money and SIM swap the dominant risk.

Uganda

Computer Misuse Act offences and penal code impersonation, with mobile money fraud the dominant pattern.

Zambia

Cyber crimes legislation and penal code fraud offences, with mobile money reversals depending entirely on speed.

Southern Africa

South Africa

If someone opens an account in your name, dispute it with the provider and keep evidence. SAFPS offers a free protective registration that alerts its member organisations.

Southern Asia

India

Sections 66C and 66D of the IT Act, a national reporting portal, and a 1930 helpline with a golden hour for freezing transfers.

Pakistan

PECA criminalises the unauthorised use of identity information, and the National Cyber Crime Investigation Agency (NCCIA) investigates.

Eastern Asia

Hong Kong

Fraud and Theft Ordinance offences, with the Anti-Deception Coordination Centre reachable on 18222.

South-eastern Asia

Malaysia

Penal Code cheating and personation offences, with a national scam response centre reachable on 997.

Philippines

Computer-related identity theft is a specific offence under the Cybercrime Prevention Act.

Singapore

Cheating by personation under the Penal Code, with Singpass misuse treated very seriously.

Northern America

Canada

Identity theft has been a distinct criminal offence since 2010, and the Canadian Anti-Fraud Centre coordinates reporting.

United States

The most developed recovery system in the world: a federal recovery plan, free credit freezes, and a statutory right to block fraudulent entries.

Caribbean

Jamaica

The Cybercrimes Act and Larceny Act cover fraud by impersonation; the TRN and NIDS are the sensitive identifiers.

Trinidad and Tobago

Fraud and forgery offences carry the case; TTCSIRT and the police Fraud Squad are the reporting routes.

Oceania

Australia

IDCARE provides free case management, and a Commonwealth Victims' Certificate gives you a court document proving you were a victim.

New Zealand

Crimes Act offences on forgery and obtaining by deception, with CERT NZ and IDCARE NZ coordinating support.

This topic is also covered for French-speaking countries · German-speaking countries.

Sources

  1. Directive (EU) 2015/2366 on payment services in the internal market, Article 71 — UK Government (GOV.UK), 2015
  2. Criminals Increasing SIM Swap Schemes to Steal Millions of Dollars from US Public — ic3.gov, 2022
  3. Credit Freezes and Fraud Alerts — consumer.ftc.gov, 2025

Official or institutional documents this page relies on, consulted on 12 October 2026. Links open in a new tab.

Content updated in . The instruments cited can change: if in doubt, confirm with the official source given.

Text written with the help of AI, under the editorial responsibility of CAPIT; human reviews are occasional (method and sources: About). This content does not replace medical or legal advice. Spotted an error? Write to us.

Locate this page in the site map